Understand any stock in simple English
Enter a ticker to learn what the company does and how it makes money.
Axway Software SA
Axway sells software that helps big companies move data safely between their own systems, their partners, and the cloud.
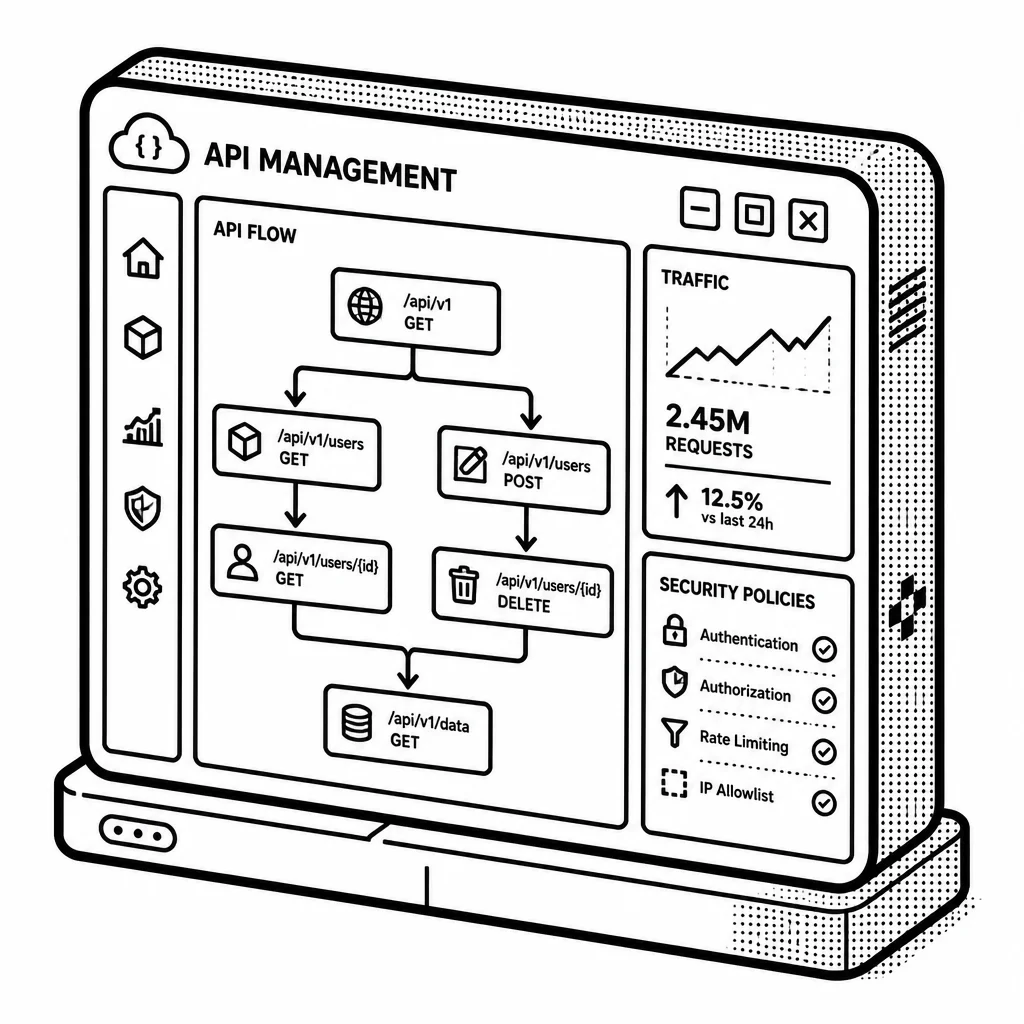
Axway is a business-to-business plumbing company. When a big bank needs to send a payment file to another bank, when a retailer's computer system needs to swap order data with a supplier, or when a hospital needs to move patient records to the cloud without losing or exposing them, Axway sells the software that makes that transfer happen safely and reliably. Its main product family is called AMPLIFY, a set of tools for integrating data across systems, managing APIs (the doorways that let software talk to other software), running B2B/EDI networks (the standard format businesses use to exchange orders and invoices), and handling large managed file transfers.
The customers are large enterprises and public organizations — banks, insurers, manufacturers, retailers, healthcare groups — that cannot afford for a file to go missing or an API to fail. They pay Axway through software licenses, subscriptions, and support contracts, and increasingly through cloud services where Axway hosts the integration work for them. The switch to subscription and cloud revenue matters because it makes income more recurring, though it also means Axway must keep investing to stay relevant against much larger rivals like IBM, Microsoft, Salesforce's MuleSoft, and Oracle — plus a crowd of smaller API and file-transfer specialists. Axway is headquartered in France and has a long history in this niche; it was spun out of another software firm in 2011 and has grown partly by buying smaller integration companies. The business is not glamorous and growth is modest, but the switching costs are real: once a company's payment files and partner connections run through Axway's systems, ripping them out is painful and risky. That stickiness is the core of the investment case — and the core vulnerability, because it can breed complacency while nimbler cloud-native competitors win new projects.
Investors should know Axway is a small-cap with a controlling shareholder structure, and its results swing with how fast customers move from old license deals to cloud subscriptions. Management has focused on expanding the AMPLIFY cloud platform and on cost discipline, and the company has used cash to pay down debt and fund acquisitions rather than pay a big dividend. The simple way to think about it: Axway sells the trusted middleman that keeps data flowing between organizations — a boring, essential job that pays recurring fees as long as customers keep trusting the pipes.
Saved answer · last researched 14 Nov 2026