Understand any stock in simple English
Enter a ticker to learn what the company does and how it makes money.
Qfin Holdings, Inc.
Qifu Technology runs an AI-driven credit-tech platform that helps banks and other financial institutions in China lend money to consumers and small businesses.
Qifu Technology is a lending matchmaker in China. It does not primarily lend its own money. Instead, it uses data and AI to find creditworthy borrowers — everyday consumers and small-business owners — and connects them with banks and other financial institutions that actually fund the loans. The borrower gets fast access to cash through a phone app, and the bank gets a pre-screened customer it might never have reached on its own.
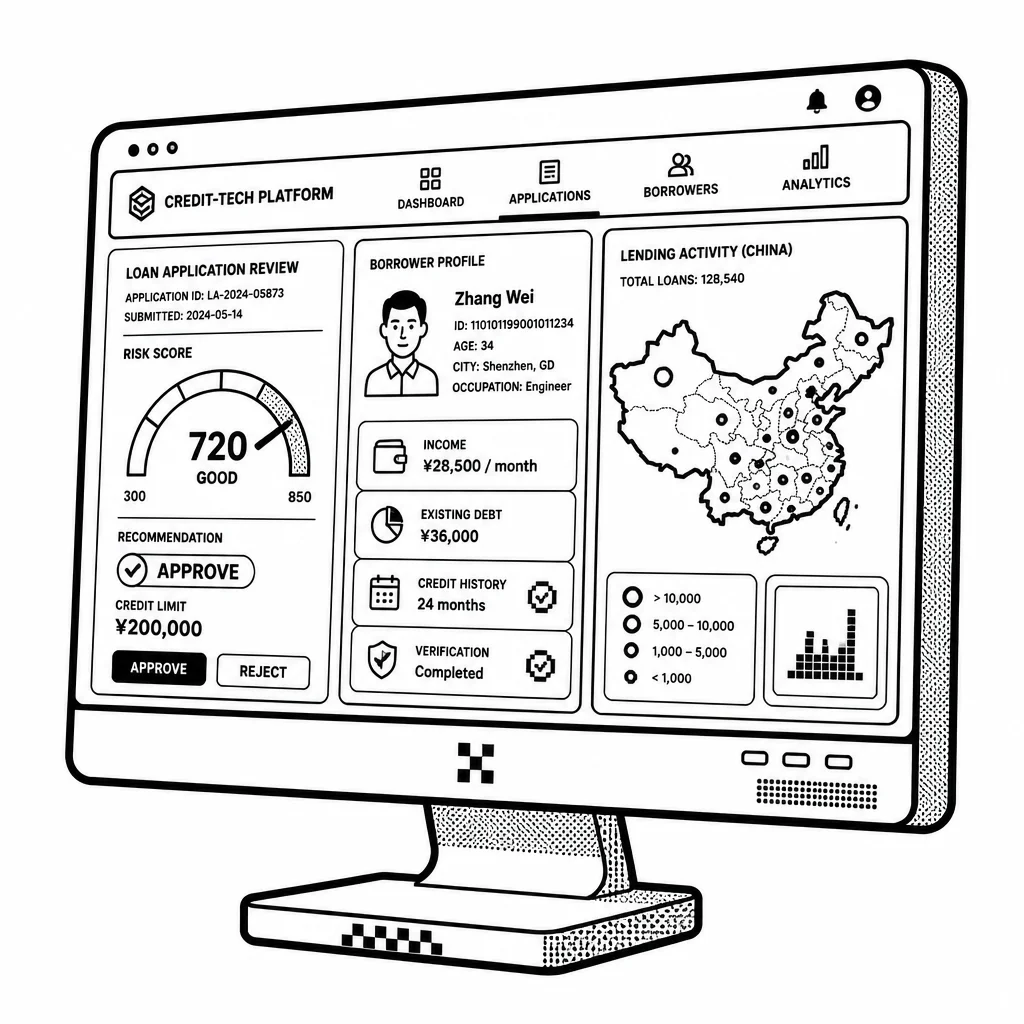
The company earns money in a few ways. It charges financial institutions fees for matching them with borrowers and for helping manage the loans after they are made. It also takes on some of the credit risk itself in certain arrangements, which means it earns more when loans perform well but eats losses when they go bad. Over time it has been shifting toward a "capital-light" model, where partners hold more of the loans and Qifu earns fees rather than interest, which makes its results less tied to the ups and downs of the credit cycle. Its customers are the financial institutions — hundreds of banks, consumer finance companies, and trusts that want to grow their loan books but lack the technology and data to reach small borrowers cheaply. Qifu's real edge is its risk engine: years of lending data, AI models that score borrowers in seconds, and a brand consumers recognize, which lowers the cost of finding and approving good customers.
The business comes with real risks. China's regulators have tightened rules on how lending platforms operate, how they share data, and how much they can charge, and consumer credit demand rises and falls with the Chinese economy. Competition is fierce from other fintech platforms and from the banks themselves as they build their own digital lending arms. Qifu has also returned cash to shareholders through dividends and buybacks, a sign it generates real free cash flow rather than just paper growth.
Saved answer · last researched 15 Nov 2026