Understand any stock in simple English
LHN Limited
LHN makes money by squeezing more value out of buildings and land — managing spaces, developing property, running facilities, and selling energy services to landlords and tenants across Asia.
LHN is a Singapore-listed company that makes money from something most people never think about: the empty space inside buildings. It takes ordinary real estate and squeezes more value out of it — managing industrial and commercial spaces, carving buildings into smaller rentable units, running the day-to-day operations of properties, and selling energy services to the people who occupy them. Its customers are mostly landlords and tenants across Asia, particularly in Singapore and Hong Kong.
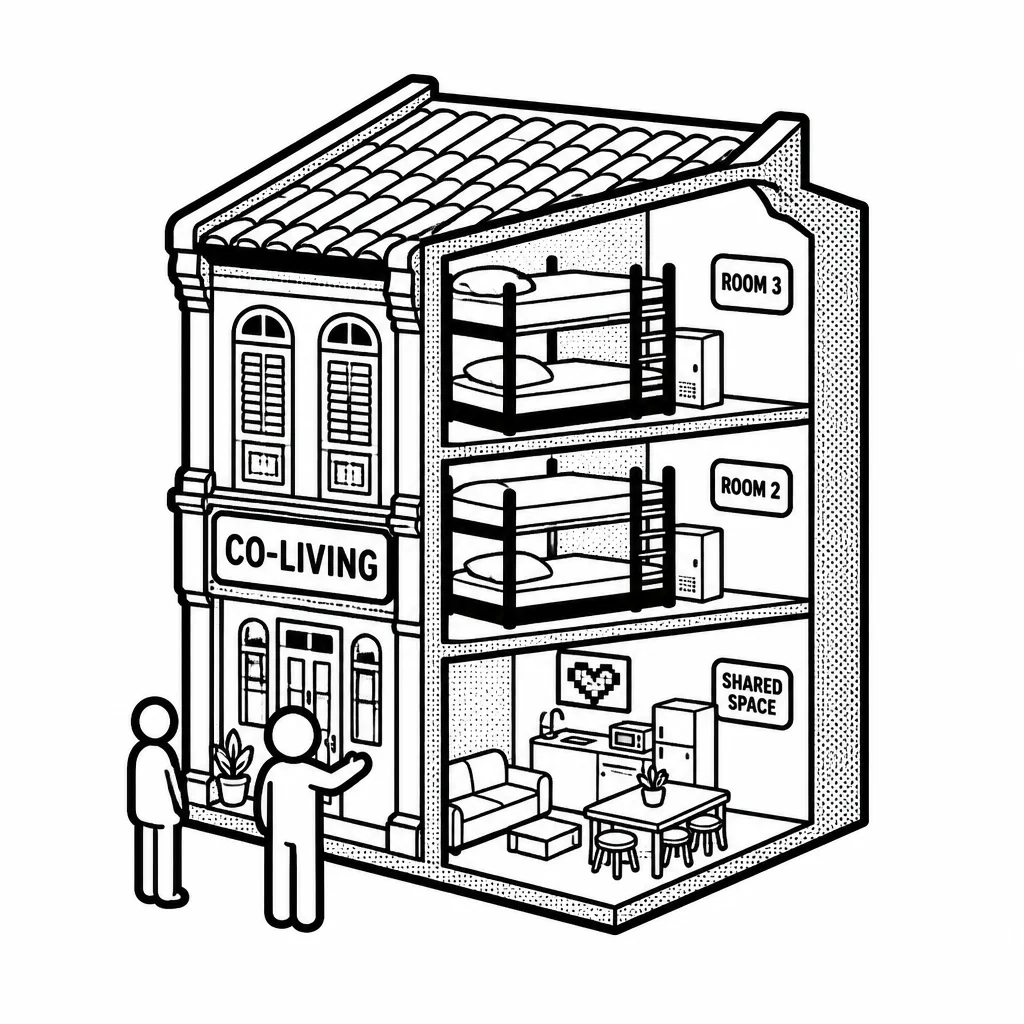
The core of the business is space optimization. LHN leases or buys larger spaces, then redesigns and subdivides them into smaller units that individual businesses can actually afford and use — things like a small workshop, a storage unit, or a compact office. It also develops property and provides facilities management, meaning it handles the unglamorous work that keeps buildings running: cleaning, maintenance, security, and repairs. On top of that, it sells energy services, which mostly means helping buildings use power more efficiently. The logic is simple: a building that runs cheaper and is filled with paying tenants is worth more to its owner, and LHN earns fees and rental income from making that happen. What makes LHN interesting is its position as a middleman between big property owners and small businesses. A landlord with a large industrial building may not want the hassle of finding twenty small tenants and managing each one. LHN does that work and takes a cut. Small businesses, meanwhile, get flexible, affordable space they could never lease on their own. This niche — industrial and commercial space in dense Asian cities where land is scarce and expensive — is where the company has built its base.
The business is not without risk. It is heavily tied to property markets and rental demand, and its results move with occupancy rates and property values. The space-optimization model requires upfront capital to lease or acquire buildings, which makes the company sensitive to interest rates and financing costs. Its growth depends on finding new buildings to transform and keeping tenants happy enough to stay. LHN has also expanded into energy services, a smaller but growing piece that fits neatly with its property focus, since building owners increasingly want help cutting power bills. The company pays dividends to shareholders and has historically grown by adding more managed space and recurring fee income rather than betting on big speculative developments.
Saved answer · last researched 17 Nov 2026