Understand any stock in simple English
Enter a ticker to learn what the company does and how it makes money.
CreditAccess Grameen Limited
CreditAccess Grameen gives small, collateral-free loans to low-income women in rural and semi-urban India, and earns money from the interest those borrowers pay.
CreditAccess Grameen is a microfinance company. It lends small amounts of cash to women in poor, rural parts of India who would never get a normal bank loan — no collateral, no salary slip, no credit history — and it makes money on the interest they pay back. The customers are mostly women running tiny businesses or households: a tailor, a small shopkeeper, someone buying seeds or a sewing machine. A few thousand rupees can be the difference between a stalled life and a working one.
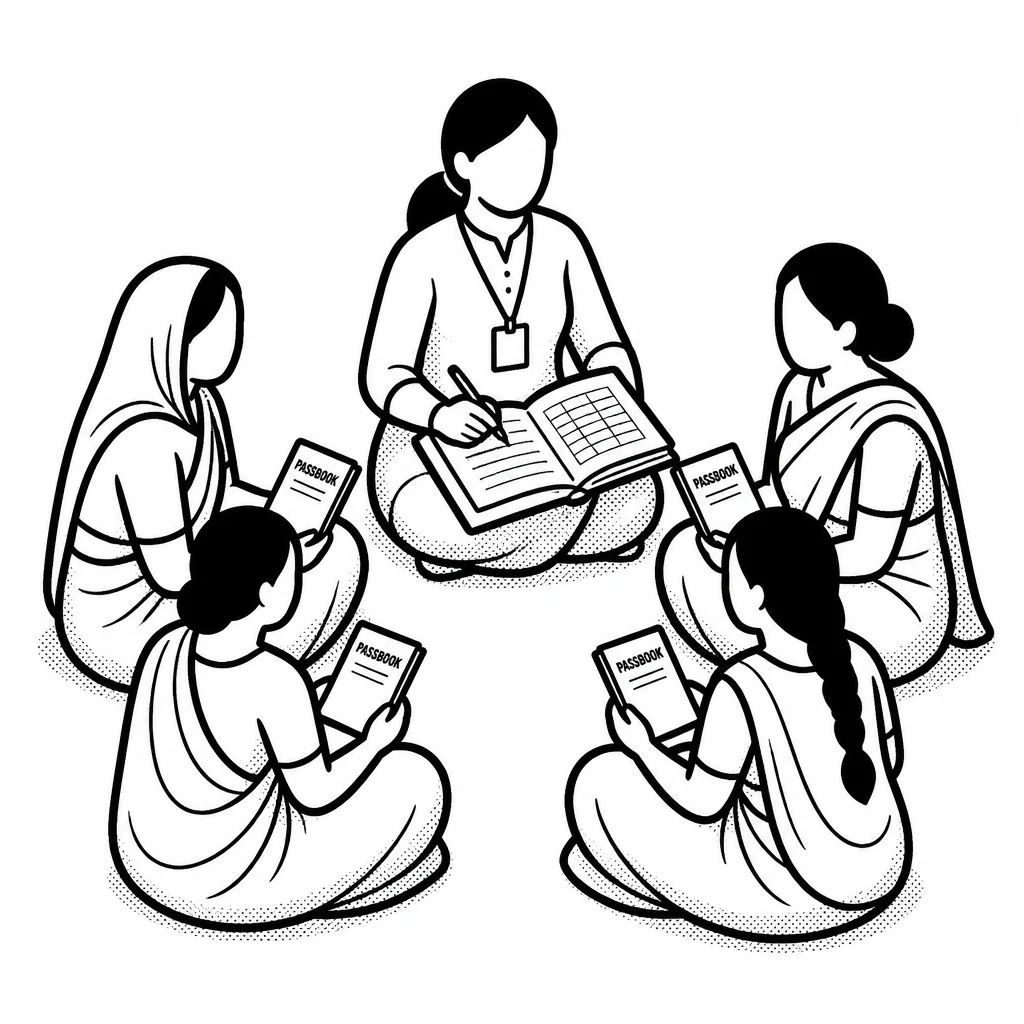
The model works because of a trick that sounds almost too simple. Borrowers join small groups, usually five women, who meet weekly with a loan officer. If one member stops paying, the whole group feels the pressure, so neighbors keep each other honest. This peer pressure, not paperwork, replaces credit scores. Borrowers repay in tiny weekly installments at the group meeting, cash gets counted on the spot, and a missed payment gets spotted the same day rather than months later at a collections department. It is relationship banking at ground level. The company — formerly called Grameen Koota Financial Services — runs thousands of branches across states including Karnataka, Tamil Nadu, Maharashtra, and Madhya Pradesh, and has grown into one of India's largest microfinance institutions. It makes its money on the gap between what it pays to borrow money from banks and what it charges borrowers, so thin margins and steady repayment are everything. That makes the business sensitive to two things: how well borrowers' incomes hold up, and how tightly the company controls costs. A drought, a bad harvest, or a local crisis can ripple through a whole branch's book.
There is real tension in this business. Charging poor borrowers high enough interest to cover costs and risk can look exploitative, and India's microfinance sector has a history of crisis and tighter rules after periods of rapid lending. CreditAccess has spent years arguing that the counterfactual — no credit at all, or a loan shark at far worse terms — is the real alternative. Either way, the company's fortunes ride on the same thing every microfinance lender's do: millions of small, honest repayments arriving on time, week after week.
Saved answer · last researched 14 Nov 2026