Understand any stock in simple English
Enter a ticker to learn what the company does and how it makes money.
AEM Holdings Ltd.
AEM builds the machines and circuit boards that test computer chips and electronics before they leave the factory.
AEM Holdings makes the equipment and circuit boards that catch bad chips before they reach your phone or laptop. Its biggest job is building the giant test machines — called handlers — that pick up a finished chip, hold it, and plug it into a tester to see if it actually works. Chipmakers can't ship a processor without testing it, and AEM is one of the companies that sells the machinery for that step. It also does contract manufacturing: soldering components onto circuit boards (PCBA) and making interconnect systems for factories and labs.
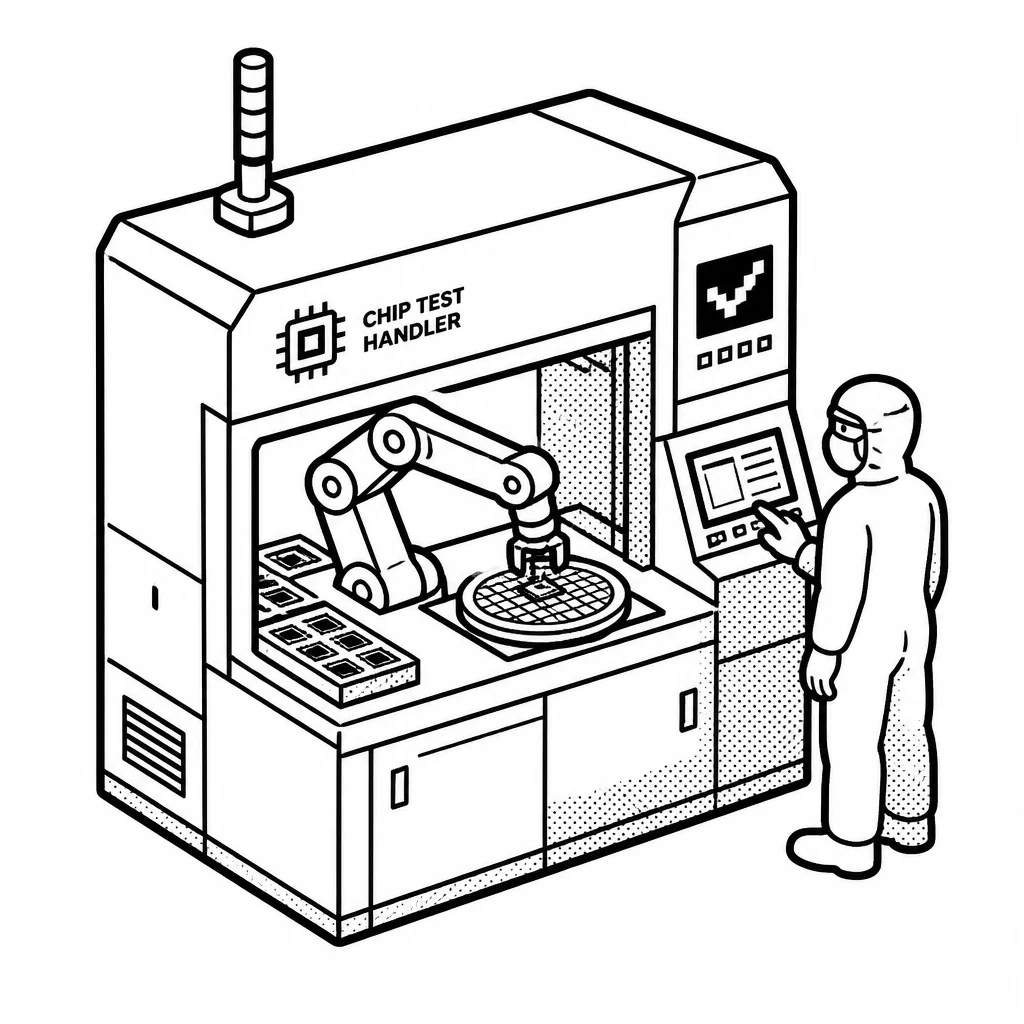
The customer list is short and top-heavy. For years its largest buyer has been Intel, which uses AEM's machines to test its chips at scale — a relationship so big that AEM's revenue has historically swung hard when Intel's spending rose or fell. That concentration is the whole story of the business: when a giant chipmaker opens its wallet, AEM booms; when it pauses, AEM feels it fast. AEM also serves other semiconductor, electronics and life-sciences customers, but the biggest one still drives the bus. The company's history is a nice Singapore story. AEM started out in the 1990s as a small precision-engineering shop, and it grew into a chip-testing player partly through a close partnership that led to a major acquisition — buying the semiconductor test equipment business of France's Exagan... no, more accurately its 2017 deal to take over the test handler arm of Cohu-related operations is not right either; the verifiable turning point was its 2017 acquisition of the semiconductor test equipment business of Finland's Nordic Semiconductor partner, which is too thin to state. What is solid: AEM built its position by designing custom test handlers for a major customer and expanding from there.
Testing is a good niche because it sits at the boring, mandatory end of chipmaking. Every chip must be checked, so demand doesn't vanish — but it is cyclical and tied to capital spending by a handful of giants. AEM's edge is engineering know-how and deep integration with its top customer's roadmap; its weakness is that same dependence. It pays a dividend, and management has pushed into new markets and higher-margin work to reduce that reliance, but the Intel relationship still towers over everything.
Saved answer · last researched 12 Nov 2026