Understand any stock in simple English
Enter a ticker to learn what the company does and how it makes money.
PT Bank Jago Tbk
Bank Jago is an Indonesian digital bank that lets people and small businesses save, borrow, and manage money entirely through a smartphone app.
Bank Jago is a bank you never have to visit. It has no branches to speak of and few real-world touchpoints; instead, everything — opening an account, saving, borrowing, paying bills — happens inside its smartphone app. It serves ordinary retail customers, the broad "mass market" of Indonesians who may never have had a proper bank account, and small and medium businesses. The pitch is simple: banking should feel as easy as using a good consumer app, not like filling out forms at a counter.
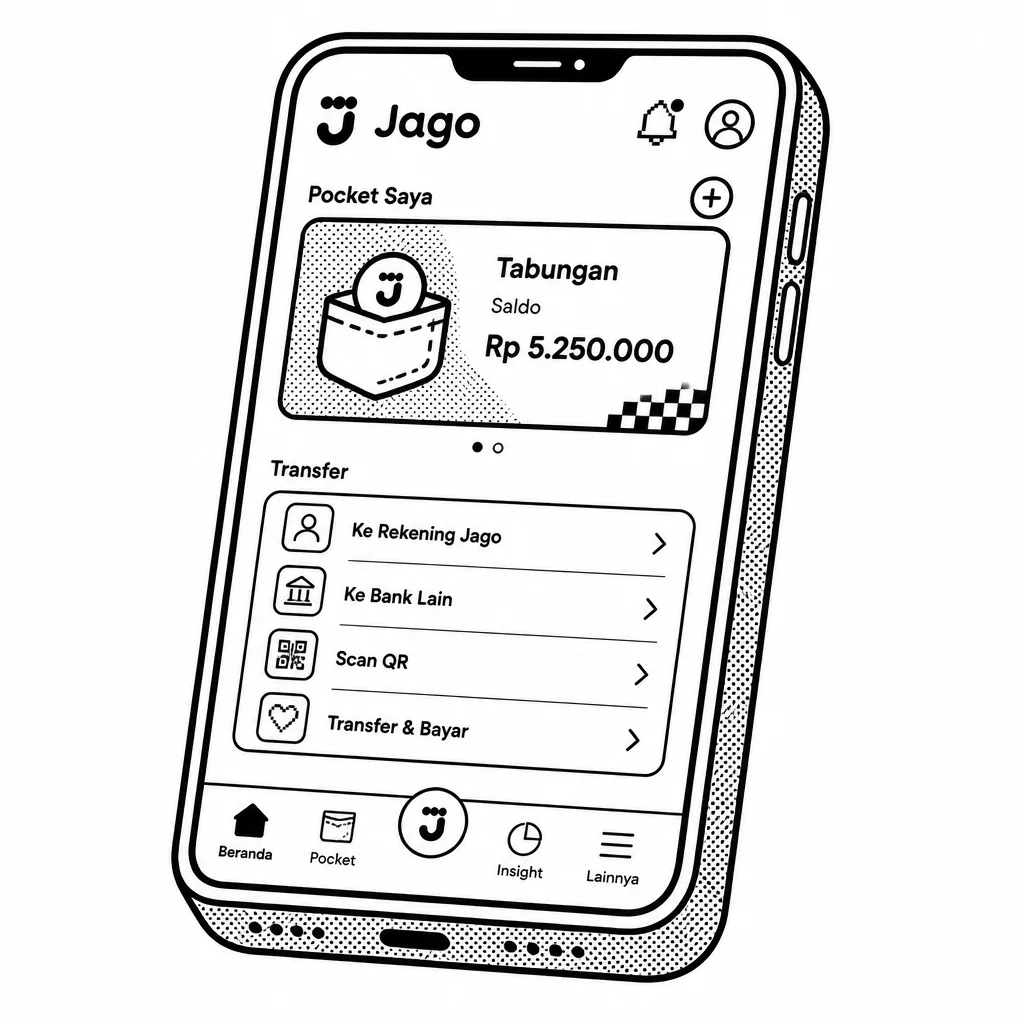
The way it makes money is classic banking dressed in digital clothes. It earns a spread by paying you a modest rate on the money you deposit and then lending that money out at higher rates, or parking it in safe interest-earning assets. It also earns fees from loans and from services like its debit card and the savings "pockets" (sub-accounts) customers use to set money aside for goals. The reason customers pick it is convenience — a slick app, quick onboarding, and features that let you split your money into different jars for spending, saving, and investing without opening separate accounts. The big strategic twist is that Bank Jago doesn't try to win customers only on its own app. It works as a "bank behind the app" for other platforms, embedding banking services into e-commerce, ride-hailing, and investment apps so their users can open a Jago account and use its services without ever leaving the partner's app. Its most famous partnership is with GoTo, the Indonesian tech giant formed by the merger of Gojek and Tokopedia, which is a major shareholder and a big source of customers. This "banking-as-a-service" approach lets Jago reach millions of people through apps they already use every day. The company began life as PT Bank Artos Indonesia, a small conventional bank, before being reborn as a digital bank under the Jago brand and renamed. It was one of the first Indonesian banks to get a full digital-banking license, which lets it operate without physical branches — a big deal in a country of thousands of islands where building branch networks is expensive. That branchless model keeps costs low, but it also means Jago lives or dies by the quality of its technology and its ability to keep regulators comfortable with a fully online bank.
Like any bank, its health hinges on lending carefully and keeping enough capital and deposits on hand. It has grown fast from a tiny base and has been investing heavily in technology and partnerships, so profits have historically taken a back seat to growth. The key risks are familiar: competition from other digital banks and fintechs, the cost of attracting deposits, and the danger that a fast-growing loan book sours if the economy or borrowers stumble. For a young bank, that trade-off between speed and safety is the whole game.
Saved answer · last researched 12 Nov 2026