Understand any stock in simple English
Enter a ticker to learn what the company does and how it makes money.
Zhongji Innolight Co., Ltd.
Innolight makes the high-speed optical transceiver modules that move data between servers and switches inside cloud data centers and telecom networks.
Innolight builds the small plug-in devices that turn electrical signals into pulses of light and back again, so data can race between servers and switches down fiber-optic cables. These optical transceivers are the plumbing of the internet's busiest buildings: cloud data centers run by the big hyperscalers and telecom equipment makers who buy them by the millions and slot them into their networking gear. When you stream a video or ask an AI chatbot a question, chances are the answer crossed a network built with these modules.
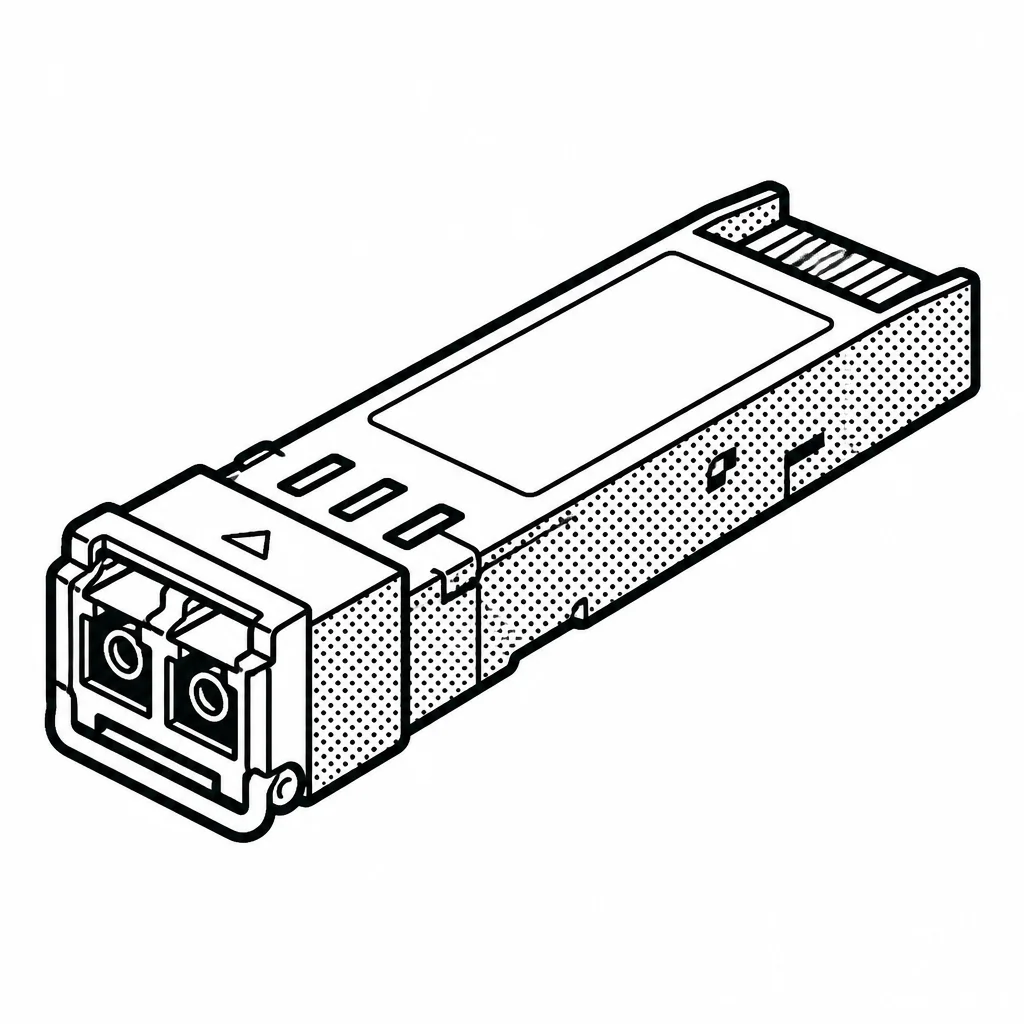
The business runs on speed. Each generation of transceiver packs more data through the same fiber, and the companies building AI clusters keep demanding faster parts, especially the 800-gigabit modules that are now the hot product. Customers don't buy on price alone; they need parts that work reliably at huge scale, and they certify suppliers carefully before switching. That gives an edge to established players who can ramp production quickly when a hyperscaler suddenly orders far more than expected. Innolight sits near the top of a crowded field. Its main rivals include Coherent and Lumentum in the West, plus Chinese peers like Eoptolink and HGTECH. Most of its manufacturing is in China, which helps on cost but leaves it exposed to U.S. export controls and tariffs on optical gear — a real risk given that American cloud giants are among its biggest customers. The company has been expanding capacity abroad, including in Thailand, to hedge against that.
The AI boom turned this quiet component maker into a stock market star: revenue and profits have surged as demand for high-speed modules outran supply. Innolight reinvests much of that cash into new factories and next-generation products rather than paying big dividends, which makes sense for a company whose fortunes depend on staying a step ahead of the speed curve. The catch is that its fate is tied to a handful of giant customers and their spending plans — great when they build, painful when they pause.
Saved answer · last researched 12 Nov 2026